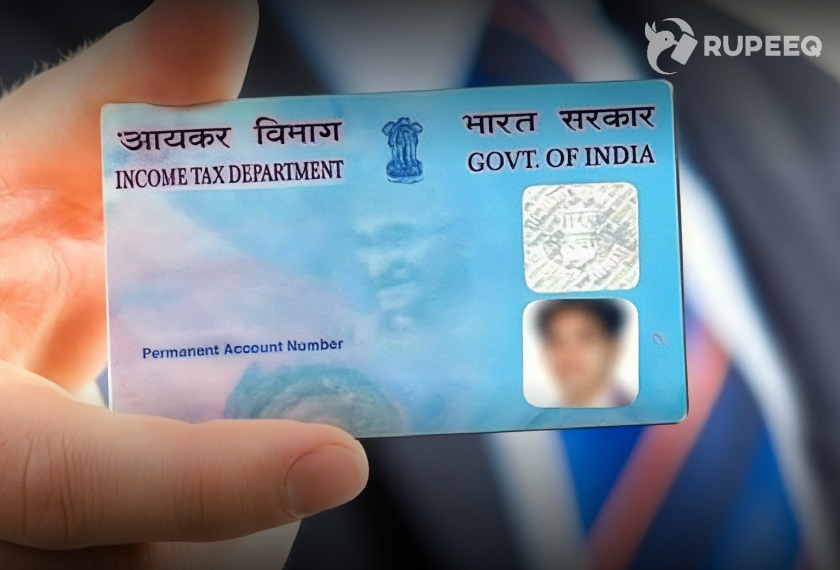
Your rent is due Friday. Your salary lands Monday. And the one thing sitting in your wallet is a PAN card.
That’s usually the moment people start searching for whether a single document is enough to borrow money. The honest answer is somewhere between yes and not quite, and the difference is worth understanding before you apply.
What It Really Means to Get a Personal Loan with PAN Card
No lender approves money on a PAN card by itself. What actually happens is that your PAN becomes the key that unlocks everything else about you.
The moment you enter it, the lender pulls your credit report, your tax footprint, and your repayment history. Everything else in the application is just confirmation.
So when digital lenders advertise an instant Personal Loan without documents, they mean minimal uploads, not zero verification. Your PAN is doing the heavy lifting quietly in the background.
Why Your PAN Carries So Much Weight
Lenders rely on PAN because it is the one identifier that cannot be duplicated or quietly abandoned.
- It links directly to your CIBIL and CRIF credit history
- It reveals existing loans and credit cards under your name
- It connects to your ITR filings and income record
- It enables Aadhaar-based e-KYC, which removes branch visits entirely
Income Tax Department data shows 78.44 crore PANs allotted to individuals as of March 31, 2025, with 66.37 crore of them already linked to Aadhaar (source).
That linkage is exactly why PAN-based lending got fast. Verification that once took days now finishes in minutes.
RupeeQ Tip: Check your credit score for free on RupeeQ ACE before you apply. Your PAN is going to surface that score anyway, so it makes sense to see it first and fix anything obvious.
Documents You Still Need Alongside Your PAN
A lean application is not an empty one. Keep these ready to avoid back-and-forth:
- PAN card, as the primary identity and credit reference
- Aadhaar or another address proof for KYC
- Last 3 months’ salary slips, if you are salaried
- Last 6 months’ bank statements
- ITR or GST returns, if you are self-employed
The full documents required for Personal Loans list stays fairly standard across lenders. If your employer does not issue payslips, a Personal Loan without a salary slip is still possible on strong bank statement history.
RupeeQ Tip: Make sure the name and date of birth on your PAN match your bank records exactly. A single spelling mismatch is one of the most common reasons clean applications get held up in verification.
Who Actually Gets Approved
Eligibility does not change just because the process is PAN-led. Most lenders look for:
- Age between 21 and 58 years
- Net monthly income of ₹15,000 and above for NBFCs
- Credit score of 700 or higher for better rates
- At least 6 to 12 months in your current job
- FOIR under 50% after adding the new EMI
If you want the precise benchmarks lender by lender, the breakdown of Personal Loan eligibility in India is a useful place to start. Borrowers with a low CIBIL score can still qualify, usually at smaller amounts and higher rates.
Steps to Get a Personal Loan with PAN Card
Step 1: Confirm Your PAN Details Are Current
Log in to the income tax portal and check your name, date of birth, and Aadhaar linking status. Outdated details stall applications more often than low scores do.
Step 2: Pull Your Credit Report First
Your PAN will expose it anyway. Look for closed loans still showing as active, or accounts you do not recognize. Raise a dispute before applying, not after a rejection.
Step 3: Match Yourself to the Right Lender
Banks usually want ₹25,000 or more in monthly income. NBFCs and digital lenders start lower. Applying to a lender that will not approve you costs you a hard inquiry for nothing.
Step 4: Complete the Digital Application
Enter your PAN, complete Aadhaar OTP verification, and upload your bank statements. Most platforms let you apply for a Personal Loan online in under ten minutes.
Step 5: Clear Verification and Accept the Offer
The lender validates your employment and bank credits. Knowing how the Personal Loan verification process works helps you respond quickly when they call.
How Much You Can Borrow on a PAN-Based Application
The amount is never decided by the document. It is decided by what the document reveals.
- Typical range: 10 to 24 times your net monthly salary
- Most PAN-led digital loans fall between ₹50,000 and ₹5 lakh
- Existing EMIs reduce your eligible amount directly
- A score above 750 often unlocks the higher end of the range
Mistakes That Slow Down PAN-Based Applications
Small errors cost more here because the process is automated. Watch for these:
- Applying to four or five lenders in the same week
- A PAN not yet linked to Aadhaar, which blocks instant e-KYC
- Bank statements from an account where salary is not credited
- Ignoring an old settled loan still marked unpaid on your report
Many Personal Loan applications get rejected for reasons that take twenty minutes to fix beforehand. Cleaning up your profile first will also speed up your loan approval process when you do apply.
Do It All From the RupeeQ App
The RupeeQ app puts your PAN to work in one place instead of five.
- Check your credit score and full credit report for free
- See matched offers from leading NBFCs before you apply
- Track your application status without chasing anyone
- Upload documents once, not with every new lender
Download the RupeeQ app or visit RupeeQ.com and see where you stand before a single hard inquiry hits your report.
Final Thought
To get a Personal Loan with PAN Card, treat the card as a window, not a shortcut. Lenders are reading what it shows them.
Keep your PAN details accurate, your credit report clean, and your lender choice realistic. Do that, and the process is genuinely as quick as it claims to be.
FAQs
-
Can I get a Personal Loan with PAN Card only?
Not with PAN alone. You will still need address proof and income evidence, though Aadhaar e-KYC makes the process largely paperless.
-
How fast is approval on a PAN-based application?
Many NBFCs approve within minutes and disburse the same day, provided your PAN is linked to Aadhaar and your bank statements are clean.
-
Does applying with my PAN lower my credit score?
A single application creates one hard inquiry with minimal impact. Applying to several lenders in quick succession is what pulls the score down.
-
What if my PAN is not linked to Aadhaar?
Instant e-KYC will not work. You can still apply through manual verification, but expect a slower process and more document requests.
Disclaimer: Interest rates, processing fees, eligibility criteria, and approval timelines vary by lender, applicant profile, and RBI guidelines. This article is for general informational purposes only. Always verify current terms with the lender before applying.